
 Udemezue John
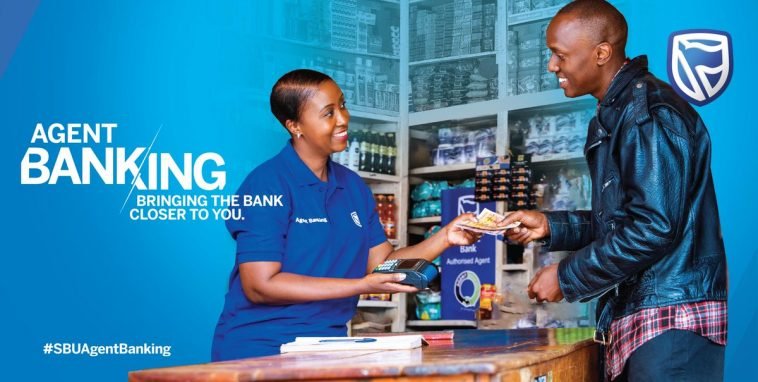
Starting a Point of Sale (POS) agent banking business in Nigeria is one of the most accessible ways to build a steady daily income. Central Bank of Nigeria (CBN) financial inclusion policies have opened up massive opportunities for individuals to provide basic financial services like cash withdrawals, deposits, utility bill payments, and airtime top-ups right in their neighborhoods.
You do not need millions of Naira to launch a POS terminal operation. With basic planning, the right location, and a reliable payment service provider, you can build a profitable daily cash-flow business.
Make sure to subscribe to this article
Understanding the POS Agent Banking Model
Agent banking allows financial institutions and Super Agents to extend banking services through third-party individuals or small business owners. Instead of walking into a traditional bank branch or standing in long ATM queues, customers visit your POS stand to carry out quick financial transactions.
As an agent, you earn money primarily through transaction charges. For every cash withdrawal, money transfer, or bill payment processed through your machine, you collect a convenience fee from the customer or earn a commission from your provider.
If you are evaluating different options for building income, reviewing how to start a small business in Nigeria can give you broader context on local business registration and planning.
How Much Capital Do You Need to Start?
Starting a POS business in Nigeria typically requires between N80,000 and N250,000 depending on your setup style and choice of provider.
Here is a breakdown of the core startup expenses:
1. POS Machine Acquisition
- Outright Purchase: Purchasing an Android POS device costs between N50,000 and N90,000 depending on the provider (such as Moniepoint, OPay, PalmPay, or Baxi).
- Caution Fee / Lease: Some traditional banks and Super Agents issue terminals on lease or caution deposit, ranging from N10,000 to N30,000. However, these often come with strict daily transaction volume targets.
2. Initial Cash Float
Your cash float is the physical money you keep on hand to pay customers requesting cash withdrawals. A starting cash float of N30,000 to N100,000 is usually enough for your first few days. As your transaction volume grows, you will need to scale your cash float to meet daily demand.
3. Location Setup
If you already own an existing shop (like a provision store, pharmacy, or salon), your location cost is zero. If you need a standalone setup, a wooden kiosk, umbrella set with a table, or small metal banner stand costs between N15,000 and N40,000.
Requirements for POS Business Registration
Getting approved as an agent is straightforward. Financial service providers require basic documentation to verify your identity and ensure regulatory compliance with CBN rules.
Basic Documents Needed
- Valid Identification: National Identity Card (NIN), Voter Card, International Passport, or Driver License.
- Bank Verification Number (BVN) and Tax Identification Number (TIN): Linked to your personal or business account.
- Passport Photographs: Two recent passport photographs.
- Utility Bill: A recent electricity bill or water bill proving your residential or business address.
- Active Bank Account: An operational bank account for settlement.
For individual agents, formal company registration with the Corporate Affairs Commission (CAC) is not strictly mandatory for initial setup with most fintech providers. However, registering a business name with the CAC helps if you plan to expand, open a corporate bank account, or apply for commercial business loans in the future.
Choosing the Right POS Terminal Provider
Your choice of payment provider directly impacts your profit margins and operational stress. Network downtime can cost you customers, while high processing charges will eat into your earnings.
Key Factors to Evaluate
- Network Stability and Signal: Choose a provider with high transaction success rates in your specific area. Moniepoint, OPay, and PalmPay are widely popular due to fast processing speed and low transaction failure rates.
- Transaction Charges: Compare charges for cash withdrawals and transfers. Most providers charge a flat rate (for example, N10 to N20) for fund transfers, and a small percentage (around 0.5% capped at N100) for withdrawals.
- Settlement Speed: Instant settlement allows money from transactions to reflect immediately in your wallet so you can transfer funds back to your bank account without delay.
- Customer Support and Dispute Resolution: Fast resolution of failed transactions or delayed reversals keeps your customers trusting your business.
While digital payments for online platforms use payment gateways (as detailed in comparing Paystack versus Flutterwave for online business), physical agent banking relies on POS hardware built for offline reliability and instant receipt printing.
Finding a High-Profit Location
Location determines whether your POS business makes N1,000 or N15,000 in net profit daily. You need locations where people frequently need quick cash or financial services but lack immediate access to working bank ATMs.
High-Performing POS Locations
- Busy Marketplaces and Shopping Centers: Traders and shoppers constantly need physical cash for transactions.
- Transport Hubs and Bus Stops: Commuters regularly withdraw cash for transport fares.
- Residential Estates and Villages: Neighborhoods located far from bank branches or reliable ATMs.
- University Campuses and Student Hostels: Students frequently make transfers and cash withdrawals.
- Filling Stations and Event Centers: High foot-traffic areas with urgent cash needs.
Always prioritize safety when picking a site. Avoid secluded areas where carrying cash makes you vulnerable to theft.
Managing Cash Flow and Liquidity
Managing cash flow effectively is the single most important daily skill in agent banking. You will balance two main reserves: your electronic wallet balance and your physical cash float.
When customers withdraw cash, your physical cash decreases while your e-wallet balance increases. Conversely, when customers deposit cash, your physical cash increases while your e-wallet balance decreases.
To prevent running out of cash during business hours:
- Build a relationship with nearby business owners (like supermarket owners or petrol station managers) who collect large amounts of cash daily. You can transfer wallet funds to them in exchange for physical cash, saving you frequent trips to commercial bank ATMs.
- Monitor peak withdrawal times—usually early mornings and late evenings—and ensure your cash float is replenished before peak hours.
- Keep a secondary bank account active so you can easily move funds across different payment channels if one bank network experiences downtime.
For broader personal financial strategies while building your business reserves, exploring low-risk investment options for Nigerian earners can help you manage your profits wisely.
Risk Management and Fraud Prevention
The POS business involves physical cash, making it a target for fraudsters if safety procedures are not followed.
Common Scams and How to Avoid Them
- Fake Bank Alerts: Never hand over cash based solely on an SMS notification on a customer’s phone. Always confirm that the funds have reflected in your own POS provider app or bank app before dispensing cash.
- Counterfeit Banknotes: Invest in a small UV counterfeit money detector light or learn to check key security threads on N500 and N1000 notes manually.
- Stolen Cards: Always verify that the name on the debit card matches the customer when processing unusually large cash withdrawals.
- Physical Theft: Do not display large stacks of money on your table. Keep cash inside a locked safe or bag that is out of public view.
Pricing Structure and Profit Expectations
Setting competitive fees helps you attract local customers while maintaining strong profit margins.
Standard charging structures across Nigeria typically look like this:
- Withdrawals between N1,000 and N5,000: Charge N100 to N200.
- Withdrawals between N5,000 and N10,000: Charge N200 to N300.
- Withdrawals above N10,000: Charge N100 per N10,000 increment depending on location competition.
- Fund Transfers: Charge N100 to N200 per transfer depending on the amount.
Assuming an average of 40 to 60 transactions daily, a well-located POS stand can generate between N3,000 and N10,000 in clear daily profit after deducting provider transaction fees. Exploring other profitable small business ideas in Nigeria can also give you ideas on complementary services like airtime recharge cards, bill payments, or retail items to sell alongside your terminal.
Frequently Asked Questions
Can I run a POS business without an existing shop?
Yes. You can operate using an umbrella stand, a small wooden booth, or a portable kiosk in a secure, high-traffic spot with permission from local shop owners or market authorities.
How long does it take to get a POS machine approved?
Most fintech providers approve agent accounts and deliver POS terminals within 24 to 72 hours once you submit valid identification and complete registration.
What happens if a transaction fails but the customer is debited?
Advise the customer to contact their issuing bank. Most failed transactions auto-reverse within 24 hours. Keep printouts of failed receipts as proof to show customers.
Scaling Your Agent Banking Business
Starting a POS agent banking business in Nigeria provides a direct path to self-employment and daily cash flow. By securing a strategic location, maintaining reliable liquidity, choosing a stable network provider, and protecting your cash float from fraud, you can quickly grow from operating a single stand to managing a network of profitable POS kiosks across your city.
What area in your town do you think has the highest demand for an agent banking stand, and what is stopping you from launching there today?

GIPHY App Key not set. Please check settings